
Vital Farms has gotten torched over the last six months - since March 2026, its stock price has dropped 38.2% to $10.01 per share. This might have investors contemplating their next move.
Is now the time to buy Vital Farms, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Do We Think Vital Farms Will Underperform?
Even with the cheaper entry price, we’re cautious about Vital Farms. Here are three reasons we avoid VITL, plus one stock we’d rather own.
1. Shrinking Operating Margin
Operating margin is a key profitability metric because it accounts for all expenses enabling a business to operate smoothly, including marketing and advertising, IT systems, wages, and other administrative costs.
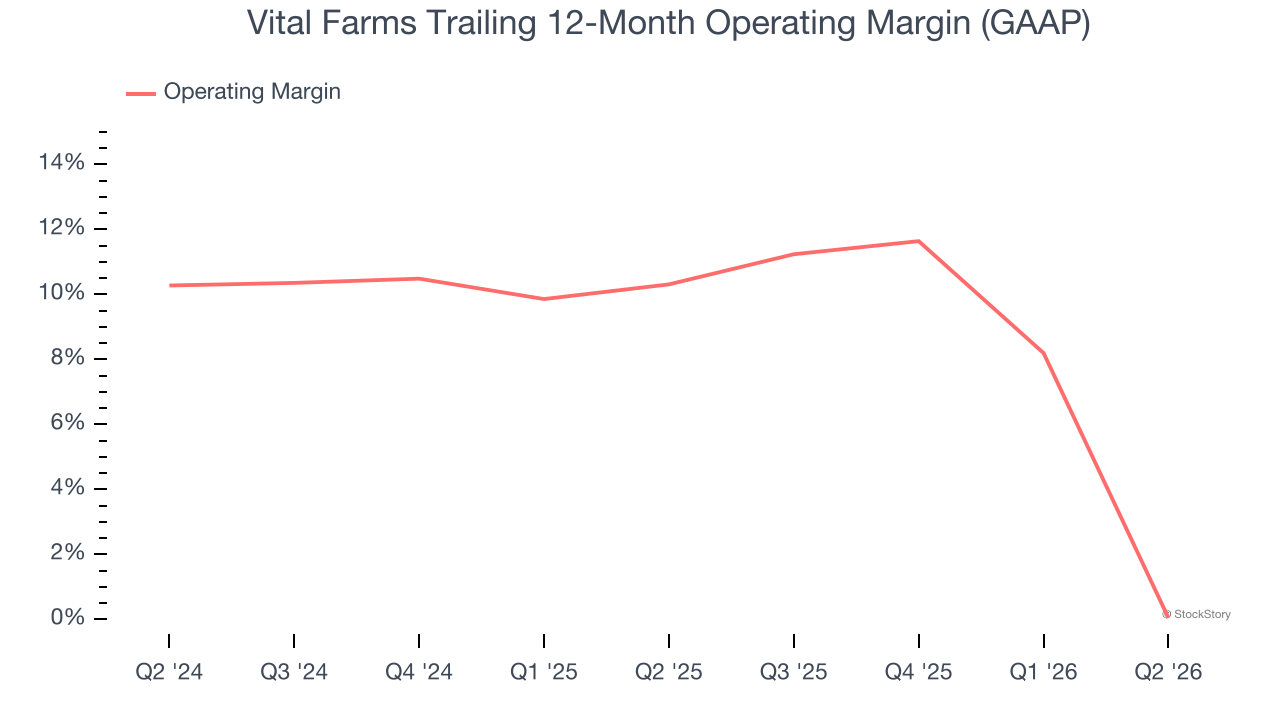
Analyzing the trend in its profitability, Vital Farms’s operating margin decreased by 10.3 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Vital Farms’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its operating margin for the trailing 12 months was breakeven.
2. EPS Trending Down
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
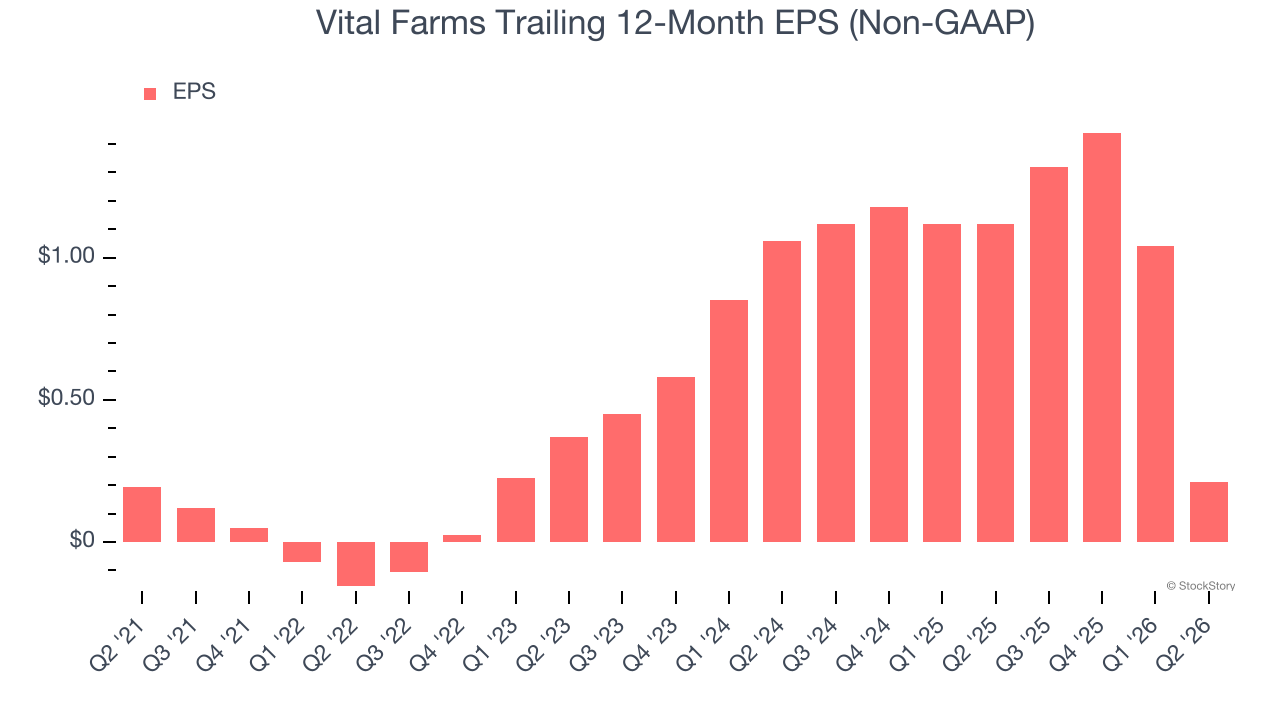
Sadly for Vital Farms, its EPS declined by 17.2% annually over the last three years while its revenue grew by 21.4%. This tells us the company became less profitable on a per-share basis as it expanded.
3. Free Cash Flow Margin Dropping
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
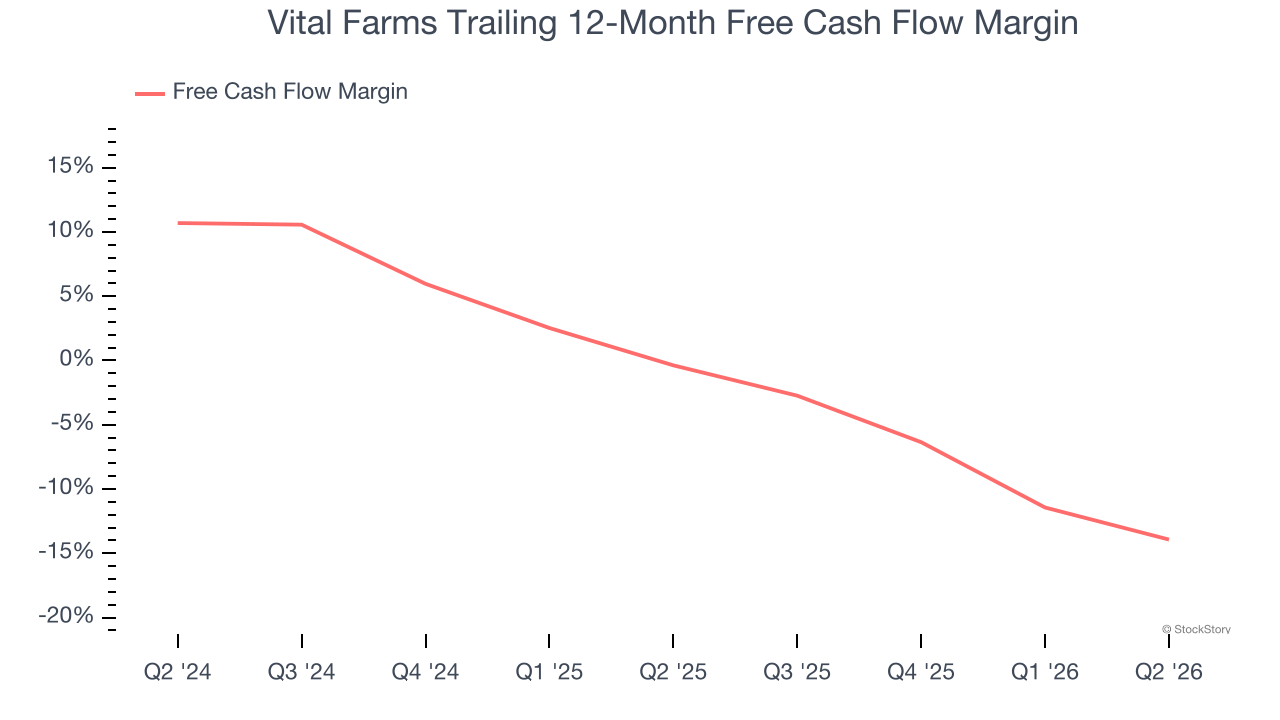
As you can see below, Vital Farms’s margin dropped by 13.6 percentage points over the last year. Almost any movement in the wrong direction is undesirable because it is already burning cash. If the trend continues, it could signal it’s becoming a more capital-intensive business. Vital Farms’s free cash flow margin for the trailing 12 months was negative 13.9%.
Final Judgment
Vital Farms doesn’t pass our quality test. Following the recent decline, the stock trades at 13.9× forward EV-to-EBITDA (or $10.01 per share). This multiple tells us a lot of good news is priced in - we think there are better opportunities elsewhere. Let us point you toward the most entrenched endpoint security platform on the market.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.