Financial data provider FactSet (NYSE:FDS) reported calendar Q3 2026 (fiscal Q4 2026) results beating Wall Street’s revenue expectations, with sales up 6.3% year on year to $634.7 million. The company expects the full year’s revenue to be around $2.61 billion, close to analysts’ estimates. Its non-GAAP profit of $4.52 per share was 4% above analysts’ consensus estimates.
Is now the time to buy FactSet? Find out by accessing our full research report, it’s free.
FactSet (FDS) Q3 CY2026 Highlights:
- Revenue: $634.7 million vs analyst estimates of $629.7 million (6.3% year-on-year growth, 0.8% beat)
- Pre-tax Profit: $144.4 million (22.7% margin)
- Adjusted EPS: $4.52 vs analyst estimates of $4.35 (4% beat)
- Adjusted EPS guidance for the upcoming financial year 2027 is $19.45 at the midpoint, missing analyst estimates by 1.4%
- Market Capitalization: $9.25 billion
Company Overview
Founded in 1978 when financial data was still primarily delivered through paper reports, FactSet (NYSE:FDS) provides financial data, analytics, and technology solutions that investment professionals use to research, analyze, and manage their portfolios.
Revenue Growth
A company’s long-term sales performance is one signal of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, FactSet grew its revenue at a decent 9.2% compounded annual growth rate. Its growth was slightly above the average financials company and shows its offerings resonate with customers.
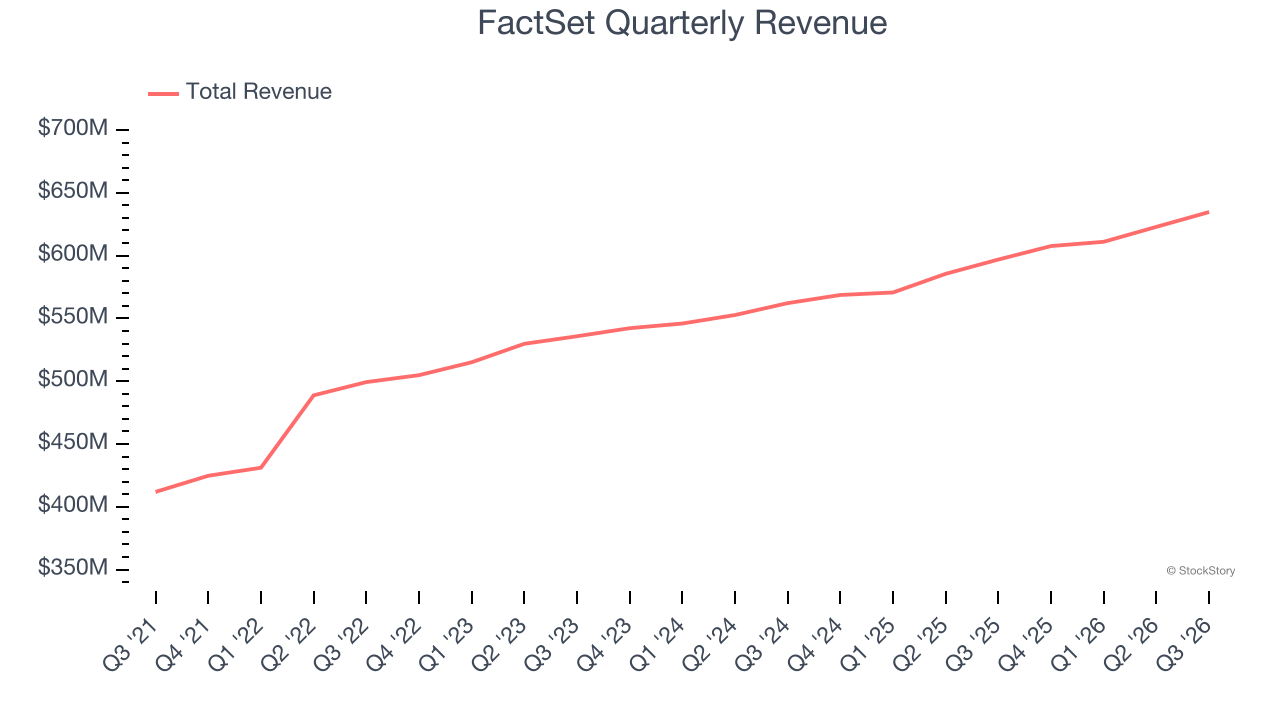
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. FactSet’s recent performance shows its demand has slowed as its annualized revenue growth of 6% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 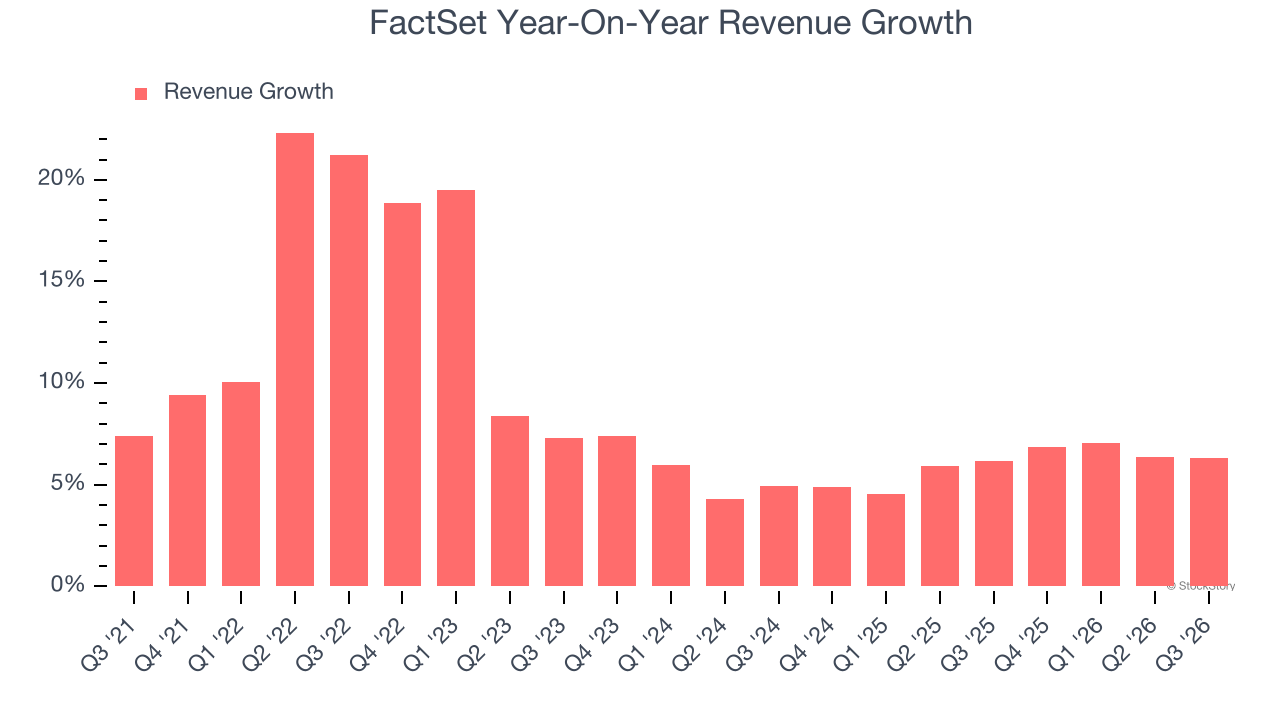
This quarter, FactSet reported year-on-year revenue growth of 6.3%, and its $634.7 million of revenue exceeded Wall Street’s estimates by 0.8%.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Key Takeaways from FactSet’s Q3 Results
It was good to see FactSet beat analysts’ EPS expectations this quarter. We were also happy its revenue narrowly outperformed Wall Street’s estimates. On the other hand, its EBITDA missed and its full-year EPS guidance fell slightly short of Wall Street’s estimates. Zooming out, we think this was a mixed quarter. The stock remained flat at $258.53 immediately following the results.
Big picture, is FactSet a buy here and now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).